Financial services are changing faster than traditional institutions can transform on their own. New technologies, evolving customer expectations, regulatory developments, and emerging digital business models are creating an environment where innovation depends increasingly on connected ecosystems rather than isolated efforts. For banks, fintechs, technology providers, and regulators, the ability to collaborate is becoming an important part of building financial services that are scalable, secure, inclusive, and responsive.
As financial institutions explore a smart banking tech expo to understand emerging solutions and industry developments, the broader lesson is becoming clear: technology creates possibilities, but collaboration helps turn those possibilities into practical outcomes. Bringing different areas of expertise together can help organisations address complex challenges while accelerating the development of solutions that respond to real market requirements.
Why Financial Innovation Can No Longer Happen in Isolation
Financial innovation once centred largely on individual institutions developing products within their own technology environments. Today, that model is becoming increasingly difficult to sustain. Digital payments, open finance, embedded services, artificial intelligence, cloud infrastructure, digital identity, and data analytics often require multiple organisations to work together.
A bank may possess customer relationships and financial expertise, while a fintech may provide specialised technology and an agile development approach. Technology providers can contribute infrastructure and advanced capabilities, while regulators establish the frameworks required for responsible innovation. When these strengths are connected effectively, organisations can develop solutions that address broader needs than any single participant could manage independently.
Fintech Partnerships Are Reshaping Traditional Banking
Fintech collaboration is increasingly influencing how financial institutions design and deliver services. Partnerships can give established banks access to specialised technologies without requiring them to build every capability internally. These relationships may involve payment platforms, digital lending systems, fraud detection tools, customer experience technologies, data analytics, digital identity solutions, or embedded finance infrastructure. Rather than viewing fintechs simply as competitors, financial institutions can increasingly consider them potential partners within a wider ecosystem.
However, successful collaboration requires more than technological compatibility. Institutions must establish clear responsibilities, governance structures, security expectations, data-sharing arrangements, and performance objectives. Without these foundations, partnerships can create operational complexity instead of delivering meaningful innovation. The emphasis, therefore, is shifting towards strategic collaboration. Financial institutions need to understand not only what a technology can do, but also how it can integrate into existing operations, regulatory requirements, customer journeys, and long-term business strategies.
The Role of Technology in Enabling Collaboration
Technology provides the infrastructure that makes many collaborative models possible. APIs, cloud platforms, artificial intelligence, data analytics, digital identity systems, and interoperable payment infrastructure can help organisations connect capabilities and exchange information more efficiently. Open APIs, for example, can enable authorised systems to communicate with one another, creating opportunities for new financial products and services. Cloud infrastructure can support scalable applications and help institutions respond to changing demand. Artificial intelligence can assist with fraud detection, customer personalisation, risk assessment, and operational efficiency.
Yet technology should not be considered the complete solution. Effective implementation also depends on governance, security, data management, regulatory alignment, and organisational readiness. Recent financial innovation discussions in Kenya have increasingly focused on areas such as AI-powered customer experiences, data analytics, biometric identity, financial crime prevention, cloud scalability, and digital transformation ecosystems. These themes illustrate how technology and collaboration increasingly intersect across financial services.
Creating Space for Knowledge Exchange
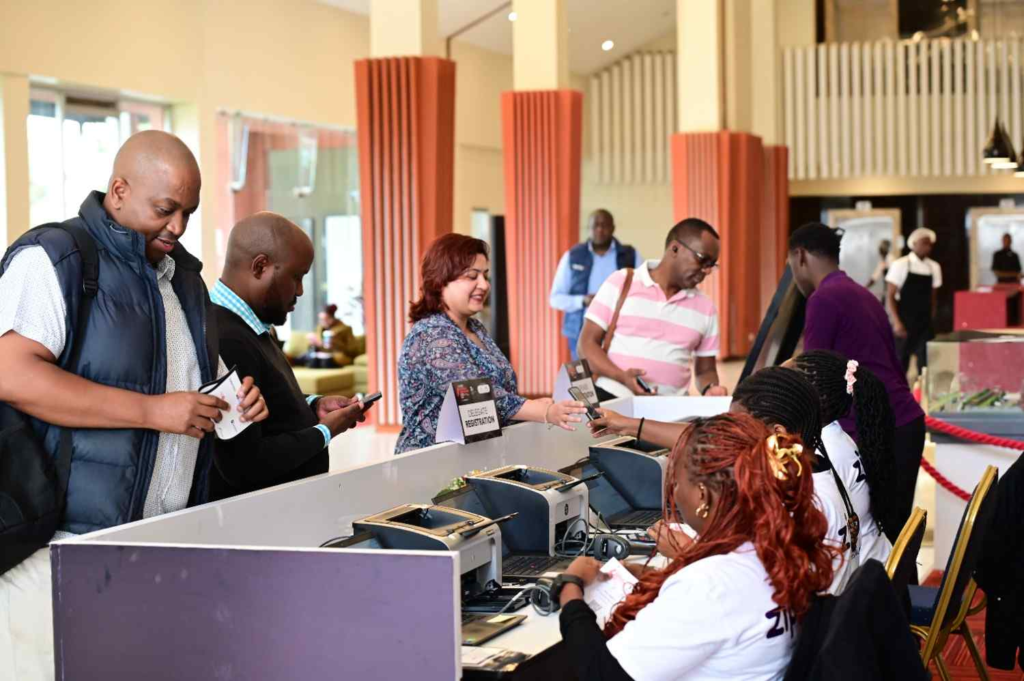
Collaboration is not limited to formal partnerships. Industry dialogue, professional networks, conferences, exhibitions, workshops, and expert-led discussions can also contribute to innovation. These environments allow decision-makers to compare approaches, understand emerging technologies, examine practical challenges, and learn from experiences across different organisations. Direct conversations can also help technology providers understand the requirements of financial institutions more clearly.
For professionals tracking smart banking Kenya, this exchange of ideas can be particularly relevant as the market continues to develop across digital payments, financial inclusion, open finance, cybersecurity, artificial intelligence, and cloud-based infrastructure. Knowledge sharing can help organisations identify common challenges before investing heavily in individual solutions. It can also encourage conversations around standards, interoperability, responsible technology adoption, and customer protection.
Collaboration and Responsible Innovation
Financial innovation must also be accompanied by responsibility. As more financial services become digital, questions surrounding data protection, cybersecurity, identity management, fraud prevention, and regulatory compliance become increasingly important.
Collaboration can help address these challenges by bringing technical, regulatory, operational, and business perspectives into the same conversation. A technology provider may understand the technical controls required for a solution, while a financial institution understands its operational environment and a regulator understands the wider implications for the market. This collective perspective can help organisations identify risks earlier and design more resilient approaches. It can also support responsible experimentation, particularly when emerging technologies such as generative AI and alternative data are being considered.
Preparing for the Next Phase of Financial Innovation
The future of financial services is likely to involve deeper connections between banks, fintech companies, technology providers, regulators, and other ecosystem participants. Institutions that understand how to collaborate effectively can create pathways for innovation while maintaining appropriate governance and risk controls.
The objective is not collaboration for its own sake. It is about creating meaningful connections that solve practical problems, improve customer experiences, expand access, strengthen infrastructure, and support sustainable growth. As financial technology continues to evolve, organisations will also need to remain open to new forms of partnership. Innovation may increasingly emerge from ecosystems where different capabilities are combined rather than from a single organisation working independently.
Conclusion
The future of financial innovation will depend not only on the technologies that emerge but also on how effectively the financial ecosystem connects expertise, ideas, infrastructure, and decision-makers. Collaboration can create a foundation for more practical, scalable, and responsible innovation while helping organisations respond to rapidly changing market expectations.
For professionals seeking a focused environment to understand these developments, World Financial Innovation Series (WFIS) – Kenya provides a platform where banking leaders, fintech innovators, technology specialists, and other financial-sector stakeholders can exchange perspectives and explore emerging solutions. Its conference and exhibition-led format brings practical industry discussions together with opportunities to discover technologies, build professional connections, and examine the developments shaping Kenya’s financial future.
